
Michael Fridjhon: Why is Burgundy 10 times more expensive than the Cape?
By Michael Fridjhon, 14 October 2026
-
Share:


12
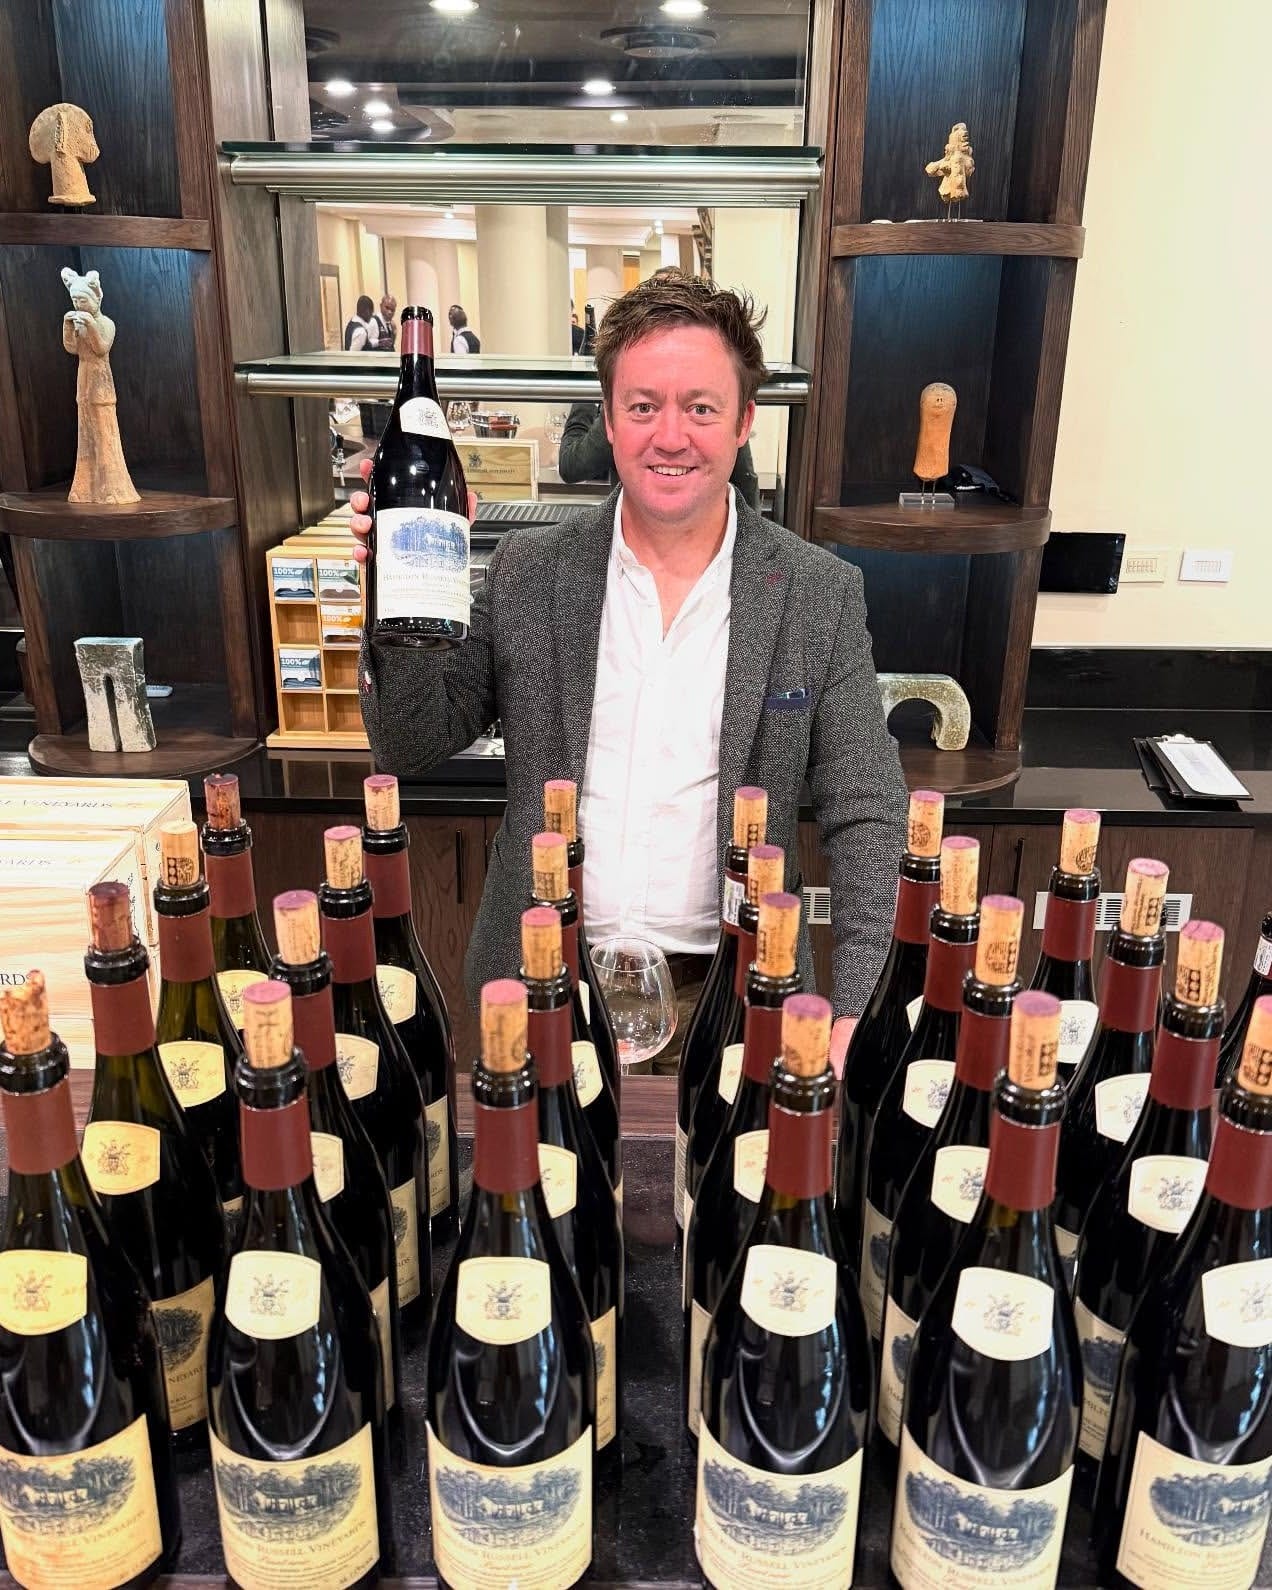
One of the abiding lessons from the famous Judgement of Paris tasting hosted 50 years ago by the late Steven Spurrier in Paris is the discrepancy between the price points of New World producers and those of their competitors in the Old World. “Unknown” (not just to the French but also to all international markets) Californian wines, selling for a fraction of what people were paying of top French wines, outperformed many of the world’s best-known wines from legendary appellations. Amongst the vanquished were Chateaux Mouton Rothschild and Haut Brion and a Batard Montrachet from Ramonet.
Very little has changed since then. Yes, a few “iconic” international wines (Grange, Opus One) have seen their prices increase to align with the middle to upper end of the market (mainly in the last two decades), likewise some “unobtainable” cult wines (Harlan and Screaming Eagle, for example). But the gap between the leading New World producers and their European counterparts has not narrowed since then. Rather, it has increased significantly over the last half century.
Quality isn’t the problem
There are no technical reasons for this pricing discrepancy. Jancis Robinson recently reported on a series of blind tastings hosted by Smith and Sheth (the new big name in Kiwi Chardonnay) of their top cuvées lined up against some Burgundy collectibles. The most expensive New Zealand wine sells for under £100. The most expensive French wine – Domaine Leflaive Montrachet 2023 – retails for over £1,100. The only wine she scored above 18/20 (it finished on 18.5/20) was the Smith and Sheth Les Graviers 2024. Almost all of the Burgundies – and certainly all of the premiers and grands crus – price well into £250+ territory. These are not small pricing differentials – you could be talking about the produce of two different planets.
Meantime a very interesting study, published originally in the International Journal of Wine Business Research, analysed production practices and business strategies between Burgundy, New Zealand and South Africa. “Beyond terroir: a comparative analysis of Pinot Noir producers and business strategies in Burgundy, New Zealand and South Africa” (Depetris Chauvin, Pinède, & Priilaid, 2024) compared human capital, equipment and the working environment. The results were not necessarily surprising, though the extent of the differences is worth sharing: “92.9% of surveyed South African Pinot Noir wineries employ staff with formal oenology degrees (versus 39.5% in Burgundy), and 60.7% hold business degrees (versus 26.7% in Burgundy). • Technological Sophistication: South African producers post the highest winery equipment index across all three regions (60.1% vs. 49.6% in Burgundy), combining modern cellar automation with meticulous hand-harvesting (96.2%).”
There’s nothing surprising about either of these two outcomes – the Chardonnay tasting or the quantification of the technical competences of New World versus Old World producers. And this is actually where we should pause, and allow ourselves the surprise which would be the most likely reaction of a Martian presented with this evidence.
The price gap has widened
Fifty years after the Judgement of Paris tasting, half a century into an era in which it is widely recognised that fine wine does not have to come from a few appellations in France, the pricing differential in favour of the Old World has actually widened considerably. In the mid-1970s you could buy DRC Montrachet for R25-00, Jadot Montrachet for R15-00 and Chevalier Montrachet for R10-50. Krug cost R9-50 per bottle, Cristal R12-50, Chateau Leoville Lascases R10-50 and Chateau d’Yquem R25-00. At the same time Alto Cabernet sold for R3-50 and Theuniskraal Gewürztraminer (the highest priced SA white wine on the list I consulted) R1-90. These numbers tell us that R25-00 per bottle was the upper limit of price tolerance even for the world’s most iconic wines, and that South Africa’s most expensive cabernet sold for exactly one third the price of a Bordeaux Super Second.
Today – and if you exclude tiny volume wannabe cult wines whose pricing is not a reliable indicator of demand – this gap has widened. Currently Kanonkop Cabernet sells for one tenth the price of Leoville Lascases. The most expensive Cape chardonnays – say Delaire-Graff Terrace Block, Kershaw Deconstructed, or Capensis – hover around R1,500, which again is no more than 10% of the price of high-end (but not unobtainable) white Burgundy.
What happens next?
Two patterns are instantly discernible: the first is that the Old World has powered ahead price-wise despite the undisputed quality of the New World offering; the second is that the stratospheric pricing is simply a measure of demand from collectors and investors. This may have peaked, and could even be on the decline. There’s also no certainty, given climate change and the economics of fine wine, that the blue-chip purchases of 2026 will occupy the top slots on the ladder in 2076. But if prices really ease (and they should – much of what has fuelled their disproportionate increases has been worldwide demand for limited resource commodities) it’s also not certain that the New World will usurp these elevated price-points: if the bubble bursts it could lead to a complete realignment for everyone.
The past half century may have broadened the supplies of fine wine (and vastly increased the number of sites supplying them) but the primary beneficiaries have been the established producers of the Old World. This means that despite everything, the New World is still playing catch-up. Maybe with climate change (New Zealand’s chardonnays grow in a place which today is much cooler than the Cote de Beaune) the virtues of these more faraway appellations will become more evident. It’s possible that the Cape and the Antipodes will be the new centres of luxury wine in 2076, and the Old World’s best producers will be battling to make a living. What is clear however is that for now the pre-eminence of the Old World, as measured in retail price premium, remains unassailed.
- Michael Fridjhon has over thirty-five years’ experience in the liquor industry. He is the founder of Winewizard.co.za and holds various positions including Visiting Professor of Wine Business at the University of Cape Town; founder and director of WineX – the largest consumer wine show in the Southern Hemisphere and chairman of The Trophy Wine Show.
-
Share:
Related articles
Opinion & Analysis
Michael Fridjhon: The great wine shakeout
16 September 2026
The world of wine is shrinking. Pretty much in every country – with very few exceptions – more vines are being removed than replaced. Less wine is being drunk, and...
3
Opinion & Analysis
Michael Fridjhon: Wine scores haven’t failed – we’ve debased them
12 August 2026
Christian Eedes’s recent piece on judging, scoring and the role of the critic was a masterly summary of the issues being debated in the admittedly rarefied space where people ponder...
4
Opinion & Analysis
Michael Fridjhon: Fine wine fame is earned one visitor at a time
15 July 2026
Many South African wine producers, especially those who are relatively recent arrivals on the international stage, lament the years of isolation – not just the 1980s as an era, but...
Louis | 14 October 2026
Burgundy and Bordeaux are in a league of their own, with history, prestige and collector demand driving prices far beyond quality alone. The same could be said of Eben Sadie’s wines within South Africa.
A more meaningful comparison would be between Cape Pinot Noir and its counterparts in New Zealand, Australia or Argentina. How do they compare on quality, recognition and price?
I still maintain that, in the price-sensitive international market, South African wines are often relatively expensive, competing with better-known regions or producers offering organic and biodynamic credentials. The value proposition of SA wines isn’t always as compelling as we might think.
Julian Wannell | 15 October 2026
I agree with your last sentence in particular
Andre Roothman | 14 October 2026
I live in Canada and we are fortunate to buy wines from all over the world. Unfortunately the selection of South African wines in my province very limited. It is mainly plonk and overpriced. However, when I am able to get some of the better South African wines, the value for money of the South African wines is clear.
Ken Forrester | 20 October 2026
I guess you’re in Ontario and the “fault” or shall we say selection of SA wines available sits in the hands of one person on the board of the LCBO. That person dictates what SA looks like, what’s the availability is on the shelves of Ontario. One person. Take the gripe to the board please.
Honest John | 14 October 2026
Rubbish. Burgundy and Bordeaux are living off their past and the snob value thereof. The quality of the top (and some not so top) ZA wine is vastly underrated – and long may it remain so as it means prices remain (vaguely) sensible, which certainly cannot be said of Burgundy and Bordeaux.
Gareth I | 15 October 2026
I have to disagree strongly on Bordeaux. Maybe at the *very* top end, but you can get really excellent Bordeaux for relatively little money in Europe. It’s known to be good value.
South African bdx blend imports not so much
Izak Jacobus Smit | 15 October 2026
Yip, there is always fact, but then there is also reality.
My point is simple and more of a fact namely, that South African’s never learned what an export culture involves. Secondly, on the reality front, we are used to be told how good our wines are instead of following what we know. It’s also not as if we are playing for the same team on the playing field. Instead, for identity we are highlighting our distinctive fynbos and architecture and things like that, instead of having a marketing campaign to promote our best wines. WOSA is open to all those that pays them and then follow their own tune, despite getting more than 50 million odd a year from Government. No wonder nothing will change. These realities speak volumes.
Julian Wannell | 15 October 2026
With reference to the title of this piece, which specifically highlights Burgundy’s price differential with “the Cape”, my answer would be that most consumers, collectors and trade buyers of Burgundy are looking for established names that reflect, by the standards & judgements of those who can afford to drink them, the best wines made out of (mainly) Pinot Noir and Chardonnay grapes.
The quality measures and accolades that apply in Burgundy – and thus determine demand, collectability, track record and prices – have been earned over many decades, in some cases many centuries. The scarcity of the top wines, driven by loyal and consistent demand that goes back a very long way, will ensure they sell out quickly with every release. These are true ‘investment grade’ wines.
You can’t compare just one region of France, where many of the best and most sought-after producers own small fragments of famous, ancient vineyards, with the entire Cape wine producing region.
Moreover, the majority of critical opinion (by those who are qualified to judge) would have it that SA has not yet reached anything like quality parity with Burgundy, when it comes to Chardonnay and Pinot Noir based wines.
All in all, a bit like asking why Volvo cars were so much more expensive than Chinese cars, 20 years ago.
The world is waking up to the best expressions of noble grape varieties from SA, but unfortunately just at the time that demand is falling; the young aren’t drinking; budgets for all but the wealthiest consumers are being cut – and the partial ‘myth’ of wine being good for our health, which ushered in so many new buyers from the emerging rich of the Far East decades ago, is being well and truly busted.
There’s no doubt that the SA wine scene in general is hugely exciting and is turfing out more and more good quality wines, year after year.
But don’t single out Burgundy – you will lose that skirmish.
Greg Sherwood | 15 October 2026
When Michael says “if the bubble bursts it could lead to a complete realignment for everyone…” this of course includes South Africa’s premium wine category. If Bordeaux and Burgundy are unable to sell wines at certain premium price points, and Bordeaux is really in dire straits at the moment, it is unlikely consumers are going to support super premium offerings from SA as an alternative. Simply won’t happen. The realignment will push prices down for eveyone. My advice to SA premium producers… investing in marketing, stories, and build a loyal (younger if possible) clientele that will follow your wines into the future. Avoid opportunistic high price fads and stick to the slow and steady pricing models that have made producers like Savage, Sadie, Crystallum, Le Riche, Kanonkop etc so collectable, consumable, and genuinely loved.
Josua | 15 October 2026
This article feels like a Greatest Hits album of wine industry tropes. Saying a Martian would be surprised by this data assumes retail price should logically track blind-tasting scores or cellar qualifications. But at the top end, wine isn’t bought as a rational agricultural product, it’s a Veblen good.
Comparing top New World Chardonnay or Pinot Noir to Grand Cru Burgundy ignores the real driver of the price gap: strictly fixed supply meeting exploding global wealth. Over the last 50 years, the number of global millionaires and billionaires has multiplied exponentially, all bidding on the exact same eight hectares of Montrachet. Technical quality in the cellar stopped being the primary driver of luxury wine pricing decades ago.
Will this change in the next few decades with climate change and shifting consumer habits? Who knows… but this article adds nothing new to the debate.
GillesP | 15 October 2026
Very well put!
Gregory David | 17 October 2026
All I can say is visiting South Africa is an absolute delight when it comes to wining and dining. The cost ratio compared to the USA makes you feel like you entered a parallel universe.